October 23, 2019

Safety-First Retirement Planning

"Two fundamentally different philosophies for retirement income planning, which I call probability-based and safety-first, diverge on the critical issue of where a retirement plan is best served: in the risk/reward trade-offs of a diversified and aggressive investment portfolio that relies primarily on the stock market, or in the contractual protections of insurance products that integrate the power of risk pooling and actuarial science alongside investments. The probability-based approach is generally better understood by the public. It advocates using an aggressive investment portfolio with a large allocation to stocks to meet retirement goals. My earlier book How Much Can I Spend in Retirement? A Guide to Investment-Based Retirement Strategies provides an extensive investigation of probability-based approaches. But this investments-only attitude is not the optimal way to build a retirement income plan." Read more on the Amazon website about the contrast between "Probability based" and Safety first" approaches to retirement income strategies.

Probability based strategies rely on investing heavily in the stock market. A safety first approach is built upon a lifetime annuity to ensure income lasts as long as you do.

Dr. Wade Pfau is one of the most respected retirement researchers writing and sharing his wisdom today. His new book, Safety-First Retirement Planning: An Integrated Approach for a Worry-Free Retirement is available at Amazon.

Check out Dr. Pfau's list of important questions to answer for the three major types of annuity products.

https://www.advisorperspectives.com/articles/2019/10/18/safety-first-retirement-planning

October 14, 2019

Pelosi's drug-negotiation proposal would save Medicare $345B

A provision in a bill introduced by House Speaker Nancy Pelosi, D-Calif., that would permit Health and Human Sservices to negotiate prices for as many as 250 drugs per year would save Medicare $345 billion from 2023 to 2029 and lower pharmaceutical industry revenues by $500 billion to $1 trillion over 10 years, according to a preliminary analysis from the Congressional Budget Office. A separate analysis from the CMS Office of the Actuary found Pelosi's plan would reduce health care spending by $480 billion and save US households $158 billion over 10 years through lower premiums and reduced cost-sharing on drugs.

Details at: https://thehill.com/policy/healthcare/465491-cbo-pelosi-bill-to-lower-drug-prices-saves-medicare-345-billion

The Seven-Year Auto Loan: America’s Middle Class Can’t Afford Its Cars

Do you wonder how your neighbor affords a new vehicle every few years? The truth is often ugly!

Ben Eisen and Adrienne Roberts explain in The Wall Street Journal: "Approximately one-third of loans on new vehicles agreed upon in the first half of 2019 were for more than six years,compared with less than 10% a decade ago, according to Experian. With increases in vehicle prices outstripping income growth, the trend is seen as an indication many households struggle to finance their lifestyle."

"For many Americans, the availability of loans with longer terms has created an illusion of affordability. It has helped fuel car purchases that would have been out of reach with three-, five- or even six-year loans."

If you've ever tried to buy a vehicle with cash you likely experienced the hard sell to finance it instead. A buyer can feel like they are being held captive by the dealership if they want to make a cash purchase. That's because "dealers now make more money on the loans their customers take than on the cars they sell."

"The average loan stretches for roughly 69 months, a record. Some last much longer. In the first half of the year, 1.5% of auto loans for new vehicles had terms of 85 months or longer, according to Experian. Five years ago, these eight- and nine-year loans were practically nonexistent."

"As a result, a growing share of car buyers won’t pay off the debt before they trade in their cars for new ones, either because the car is in need of repairs or because they want a newer model. A third of new-car buyers who trade in their cars roll debt from old vehicles into their new loans, according to car-shopping site Edmunds."

And people wonder why so few Americans are financially prepared for retirement!

How a kid’s allowance can teach money management skills

"Teaching children about money management is a big job for parents. Money talk often starts by paying an allowance. According to new research from the American Institute of CPAs (AICPA), two-thirds of parents (66%) give their child an allowance at an average of $30 a week. An allowance is just part of a larger conversation about effective financial management. Parents must make sure the lessons sink in."

"The good news is that nearly half of parents (49%) say they take time to teach their child about money at least once a week. However, nearly a third (32%) say they only teach their children about money no more than once a month, including the 7% who admit they never teach their kids about money."

Of course, much of what children learn about money management from their parents comes from daily observation. Parents who think they don't teach their children financial lessons are kidding themselves.

The article explains how parents can make decisions about how much allowance to give, which should vary with age. Ideas on how to teach children prudent money skills are also addressed. Check out: https://blog.aicpa.org/2019/10/how-a-kids-allowance-can-teach-money-management-skills.html#sthash.ymIVwxYO.dpbs

October 9, 2019

Help choosing a college major and potential career

The Utah legislature mandated creation of a website to help college students choose a major and explore career options. Check out: https://www.utahfutures.org/

It is still a work in progress with features under construction. It's a good way for high school and college students (and their parents) to explore the important decisions facing post-secondary students.

 Thanks to Eric S. Peterson, Tori waltz, and McKhelyn Jones writing for The Salt Lake Tribune. 10/9/19

September 21, 2019

How to afford college

"COLLEGE STUDENTS who borrow graduate with an average $37,000 in loans. While many people believe loans are the only way to finance a college education, that’s simply not the case."
Author Kristine Hayes is a departmental manager at a small, liberal arts college.

Here are five ways to get an advanced education while minimizing debt:"

1. Stay close to home.

2. Comparison shop. On paper, private schools typically appear to cost more than public institutions, but it’s worth digging into the details.

3. Scholarships. Billions of dollars in scholarships are given to college students every year.

4. Condensed degree programs.

5. Tap your employer. Some employers offer tuition reimbursement programs

"Many hospitals offer these types of programs for students interested in nursing. It’s even possible to attend medical school for free. Kaiser Permanente recently announced that the first five cohorts of students to attend its new medical school will pay no tuition. With medical doctors typically graduating with nearly $200,000 in debt, Kaiser’s program will no doubt generate significant interest."

 Read the full article for details: https://humbledollar.com/2019/09/educated-consumers/

10 Alternate Ways to Pay for Long-Term Care

10 Alternate Ways to Pay for Long-Term Care

Don't count on Medicare to pay for nursing home, assisted living or ongoing home health care. Medicare benefits for that type of care are typically only available after a hospitalization or injury and for a limited duration. While Medicare isn't an option, here are 10 alternatives that are:

• Group Long-Term Care Insurance

• Short-Term Care Insurance

• Life/Long-Term Care Insurance

• Health Savings Accounts

• Long-Term Care Annuities

• Life Plan Communities

• Veterans Benefits

• Home Equity

• Pensions or Social Security

• Medicaid

 Source: https://money.usnews.com/money/personal-finance/family-finance/articles/the-high-cost-of-long-term-care-insurance-and-what-to-use-instead

September 18, 2019

Retirement Income Security Evaluation Score (RISE Score™)

Retirement Income Security Evaluation (RISE) 
“evaluates just where you fall in terms of having steady income in retirement, much like a credit score, on a zero to 850 scale.”

“Consumers can access the tool online. After inputting factors such as the Social Security income you expect, any pension income you may have, how much you have saved and your monthly living and medical expenses, you can see how well you will fare financially in retirement.”

The tool is aimed at individuals ages 45 and up with investable assets of $75,000 to $2 million.

Check out the RISE score at: https://www.retireyourrisk.org/rise-score/

“The purpose of the Retirement Income Security Evaluation Score (RISE Score™) is to provide you with an estimated measure of income security to help you determine whether you're on track with your current retirement income plans. The RISE Score™ can help you assess how well your retirement portfolio will cover basic living expenses and health care costs in retirement. The RISE Score™ is also designed to help answer this simple question: How can my retirement security potentially be improved through the addition of lifetime income solutions in my retirement planning strategy?”

September 12, 2019

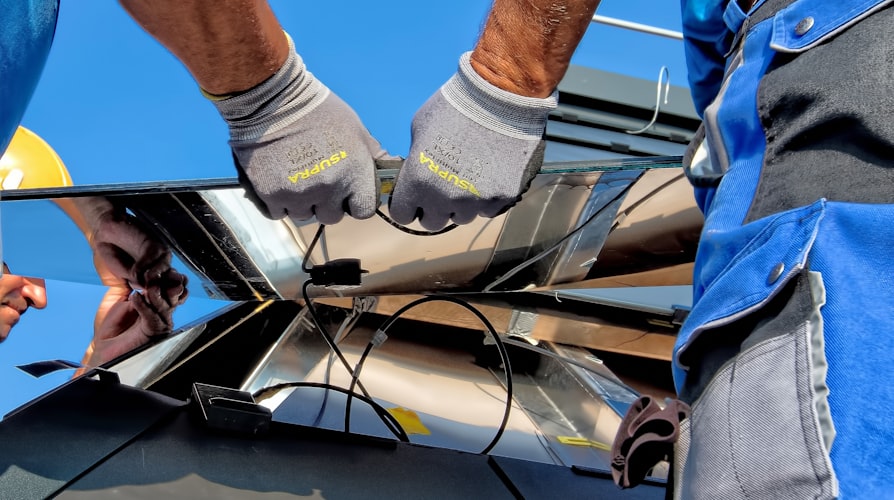
Don't wait to install solar panels

"Installing solar panels is expensive, but if you have the money, now might be the time to act. That’s because the investment tax credit, which offers significant deductions for installing a solar energy system, is set to expire soon."

"If your system is hooked up and running before the end of the year, you’ll be able to deduct 30 percent of the installation costs from your tax bill. In 2020, the tax credit will fall to 26 percent. In 2021, it drops to 22 percent, and, in 2022, it will be phased out for residential customers."
Source: NYTimes.com/climate

September 3, 2019

Small IRA, 401(k) differences can lead to big tax consequences

Writing for The Wall Street Journal, tax expert Laura Saunders explains the necessity of carefully reading the tax rules that affect the use of IRA and 401(k) funds. Failure to adhere to IRS regulations can result in a large unexpected tax bill. Especially if you are taking an early withdrawal, double check advice from a tax professional to ensure you won't owe a tax penalty.
"Because tax-favored retirement accounts are supposed to be for retirement, the rules often impose tax and a 10% penalty on withdrawals before age 59½. Younger IRA owners who take out up to $10,000 to purchase a first home don’t owe the penalty, while younger 401(k) participants do."
“The IRA and 401(k) rules are full of these booby-traps, and they hurt a lot of smart people who aren’t retirement experts,” says Natalie Choate, an attorney and retirement-plan specialist.

Education-expense withdrawals. Payouts before age 59½ from an IRA that are used for higher-education tuition, books and other costs are exempt from the 10% penalty. Similar withdrawals from 401(k) plans incur it.
 
Age 55—59½ payouts. Savers don’t owe the 10% penalty on withdrawals from a 401(k) before age 59½ if they were at least 55 in the year they left their job. But a 10% penalty applies to IRA withdrawals before the owner is 59½, except for certain exemptions.

Borrowing. Many 401(k) plans allow participants to borrow from them. Borrowing against an IRA is prohibited.

Creditor protection. Employer-provided plans such as 401(k)s are better shielded from creditors than are IRAs. 
Financial Planning for Women does not sell, rent, loan, lease or otherwise provide any personal information collected at our site to any third parties.